


By Riley Kaminer
A few years ago, Paolo Fidanza was staring at an offer most startup founders dream about: $200 million in capital, at a $400 million valuation. But the fine print told a different story. Accepting it would’ve meant giving up control of KEO World, the fintech company he launched during the early months of the pandemic. So he walked away.
Half his team thought he was crazy. Payroll was tight. The stress was real.
“I said, I’m not giving away the company. I have a vision, and I’ll prove it to you,” Fidanza told Refresh Miami.
Fast forward to today, and that decision is looking pretty smart.
KEO World, founded in Miami in April 2020, has become a major player in the B2B fintech space across Latin America. After proving its tech by lending directly in Mexico, the company now powers bank-backed credit solutions in three countries and has partnerships with global names like American Express and BTG Pactual.
Its standout product is a patented B2B payment processor that lets businesses use credit cards to settle supplier payments with customized terms, without worrying about chargebacks or the usual limits. What began as a lender-led pilot with American Express in Mexico has grown into a tech-driven joint venture model, with banks licensing KEO’s platform to serve their own customers.
By the end of 2023, KEO had processed more than $1 billion in transactions in Mexico alone, up 64% from the previous year, and became Amex’s largest B2B transaction partner globally. It has since launched in Brazil and Canada, and is currently finalizing partnerships with three major international banks.
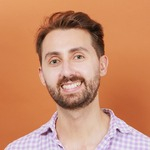
“We’re not a lender. We’re a tech company,” said Fidanza, founder and CEO [pictured above]. “Lending was always just a means to prove the product worked.”
That product keeps evolving. In 2024, KEO rolled out a new layer of infrastructure: blockchain-based payment rails that allow companies to settle B2B invoices using stablecoins, credit cards, or even traditional payment methods like ACH and wires – all through the same interface. The tech can tokenize KYC data and NFTs invoices, enabling more secure and efficient transactions. The system is already in use in Canada and Brazil.
But it all started in Miami, where Fidanza moved after exiting a previous tech company in Los Angeles.
“I couldn’t have built this in California,” he said. “Miami gave me the connectivity to Latin America, a multilingual, multicultural talent pool, and the kind of creative energy that drives innovation.”
The company’s 110-person team now spans Mexico, Colombia, Brazil, Canada, and the U.S., with Wynwood as its main base.
As for advice to other early-stage founders?
“Be resilient,” he said. “You’ll hear a lot of no’s. Use them to fuel you. And second: details matter. Don’t rush. Don’t ship ‘good enough.’ Ship great.”
Fidanza’s story is a reminder that sometimes the best move isn’t chasing the biggest check – it’s sticking to the vision. Even when it hurts. Especially when it hurts.

READ MORE IN REFRESH MIAMI:
- KEO World pioneers unique credit line model to bring financial inclusion to underserved businesses
- KEO World raises $20 million to expand B2B BNPL platform
- Boopos acquired by Founderpath in an eight-figure deal, paving the way for more SaaS M&A financing
- Finally secures $10M to develop AI-powered small business bookkeeping platform
- Tienda Pago collects $12M Series B to promote financial inclusion in Peru and Mexico
- OpenEvidence hits $15B valuation as its ambitions move far beyond medical search - September 25, 2026
- This October, Smart City Expo Miami returns for seventh edition focused on urban intelligence - September 24, 2026
- Father-son startup ClaimAngel is taking on the high cost of lawsuit funding - September 23, 2026